


With the World Cup lighting up American stadiums this summer, the U.S. economy has been putting in a mixed performance on the field — flashes of brilliance mixed with a few uncharacteristic turnovers. June’s labor market report came in soft, with just 57,000 jobs added and sizable downward revisions to prior months, though the unemployment rate held steady at 4.2%. Inflation, meanwhile, cooled more than expected as energy prices eased. Retail sales got a boost from World Cup tourists filling seats and wallets alike, even as spending elsewhere showed some fatigue. Fans from around the globe flocked to see firsthand why so many consider America the greatest country on earth, and their spending helped carry consumer activity through the month. Behind the scenes, private credit had a rougher go of it, as retail-driven redemptions accelerated across BDC and interval funds in the second quarter while institutional investors viewed the pullback as a buying opportunity. Abroad, the eurozone looked like a squad finally finding its footing after a rough stretch, while Taiwan and South Korea continued their run as breakout stars of the emerging-markets tournament, riding the global AI investment wave. Just as anticipation built for the tournament’s final rounds, markets are gearing up for their own high-stakes matchup: Q2 earnings season. The S&P 500 is expected to deliver full-year profit growth near 25%. Still, with geopolitical tensions in the Middle East threatening to disrupt the run of play through energy prices, investors will want to keep their eyes on the clock as we head into the back half of the year.
Labor markets are hanging in while inflation cools more than anticipated in June!
- Job growth in the U.S. slowed a bit in June with only 57,000 new jobs added to the economy, below the 115,000 expectation. The unemployment rate, however, dropped to 4.2%, largely due to a slump in the labor force participation rate, which fell 0.3% to 61.5%, the lowest rate since March 2021. Prior months also saw significant downward revisions — the May total, which had been much stronger than economists had anticipated, was cut by 43,000, while April’s figure came down 31,000 to 148,000 as the report showed labor market growth significantly slower than previously thought. Professional and business services contributed the most, with a gain of 36,000. Social assistance added 25,000 and healthcare employment rose by 22,000. Wages grew 0.3% month-over-month (M/M) or 3.5% year-over-year (Y/Y).
- Consumer prices rose 3.5% annually in June, less than expected as energy prices eased to near pre-Iran levels. The June CPI report showed headline inflation fell 0.4% M/M, but rose 3.5% Y/Y. Core CPI, which excludes food and energy, was flat M/M but increased at an annual clip of 2.6%. The easing of prices came from a decline in energy and a decrease in services costs, particularly for housing. Energy declined 5.7% M/M, but still gained more than 15% Y/Y. Food prices jumped 0.2% in June and shelter costs increased just 0.1%. The Fed’s preferred inflation gauge, the PCE Index, showed annual increases of 4.1% on headline inflation and 3.4% for core PCE. We believe the Fed will remain patient with any future monetary action until there is more clarity with the Iran conflict and energy prices. It is important to note that energy prices are on the rise again with the renewed strikes in the Middle East.
Retail sales get a World Cup boost & PMIs continue to show resilience of the U.S. economy
- Spending at U.S. retailers last month was weaker than expected, despite the World Cup drawing tourists from around the world and online sales events. Retail sales rose 0.2% in June from the prior month, down sharply from May’s revised 1.0% increase. Excluding sales at gas stations, spending in June was up by a solid 0.7%. Overall spending was buoyed by the World Cup and Amazon’s Prime Day although spending at gas stations declined 5.3%. Consumers remain resilient but the challenge will be if the spending trends can continue in the face of rising energy prices and continued uncertainty over economic growth and geopolitical developments.
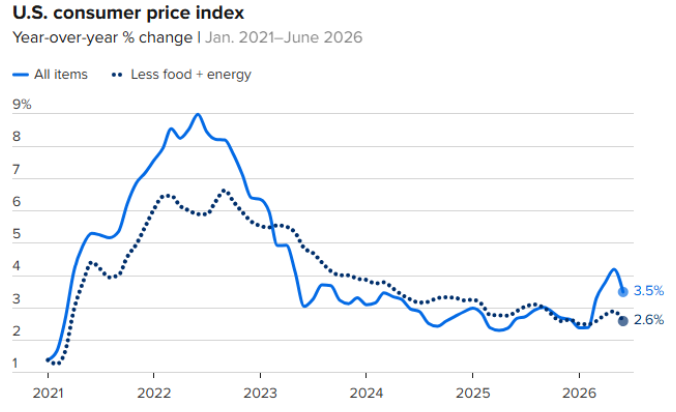
U.S. consumer price index — Year-over-year % change, Jan. 2021–June 2026. Source: U.S. Bureau of Labor Statistics
- Manufacturing activity in the U.S. softened a bit in June but remained firmly in expansion territory. The ISM Manufacturing Index fell from 54.0 in May to 53.3 in June with weakness registered in the production and new orders sub-components. Employment strengthened last month but the prices declined. Activity in the service sector also weakened modestly last month with the ISM Services PMI declining from 54.5 in May to 54.0 in June. Employment strengthened while new orders, production, and prices all fell in June.
Eurozone may need the paddles to revive its flat-lining economy!
- After two months of moderate declines in eurozone business activity in April and May, the latest S&P Global PMI survey data signaled a stabilization of the economy at the end of Q2. The Composite PMI hit a three-month high of 50.0 in June, up from 48.5 in May. While France and Germany remained in contraction territory, stronger expansions from Italy, Spain, and Ireland boosted overall business activity. Service sector activity remained in contraction territory, but June saw increased activity, boosted by an expansion in employment. The eurozone continues to struggle with any sustainable level of growth.
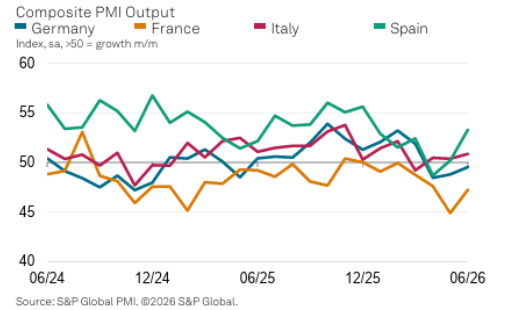
Composite PMI Output — Germany, France, Italy, Spain (Index, sa, >50 = growth m/m). Source: S&P Global PMI, ©2026 S&P Global.
Bring on more Chinese stimulus; Taiwan & South Korea continue to lead the EM growth story!
- China’s economy expanded by 4.3% in Q2, its weakest pace since Q4 2022. The weak print reinforced calls for more policy stimulus as an accelerating slide in investments deepened the strain on growth, while consumption remained subdued. China’s Q2 growth came below the PBOC’s full-year growth target range of 4.5% to 5.0%. Robust industrial production and exports tied to the global AI investment boom continue to power headline growth but trends in private investment and consumption are a bit troubling and may require further support measures. Exports remain the bright spot in an otherwise cooling economy. Other key data showed retail sales rebounded 1.0% in June and industrial output surged 5.3% Y/Y.
- Many economists have raised their growth forecasts for South Korea over the past few months as the country continues to ride the wave of global AI spending. Economists now expect 4.0% GDP growth for the current fiscal year, up from about 1% at the start of the year. Taiwan has experienced a similar growth boom, primarily led by the surge in semiconductor exports to fuel the AI infrastructure buildout.
U.S. & EM EPS are nothing short of remarkable
- As we embark on the Q2 earnings season in the U.S., expectations are high after the S&P 500 posted ~29% annualized growth in Q1. The expectation for Q2 sits at 24.7% with revenues forecast to grow 12.8%. Energy (+125%), technology (+63%), and materials (+35%) are projected to see the highest earnings growth in Q2 while healthcare (-18%) is the only sector expected to report a decline. Earnings are forecast to grow north of 20% in Q3 and Q4 with full year calendar 2026 growth projected to be ~25%. One remarkable note to point out is that despite the very strong earnings environment this year, growth is still expected to be 18% in 2027. The S&P 500 entered 2026 trading at a forward P/E multiple of 22x, but that has fallen to 20.3x due to strong earnings growth. These remarkable earnings growth figures compare to 17% growth expected in the MSCI EAFE Index and 65% growth projected in the MSCI EM Index. Most of the EM growth is coming from just a handful of AI memory related names from Taiwan and South Korea.
Will the environment for active management improve any time soon?
- The past year has been difficult for active management in traditional long-only equity strategies as well as certain fundamental long/short equity funds. Correlations were elevated due to geopolitical/macro events and dispersion was lower than historical averages. Although we do not recommend active management in certain more efficient asset classes, it is important to note that the environment has improved in recent months. Three-month implied and realized correlations have fallen to multi-year lows and dispersion at the sector level has increased with some violent market rotations. In a perfect investing world, the combination of low correlation and high dispersion typically presents an attractive backdrop for active management.
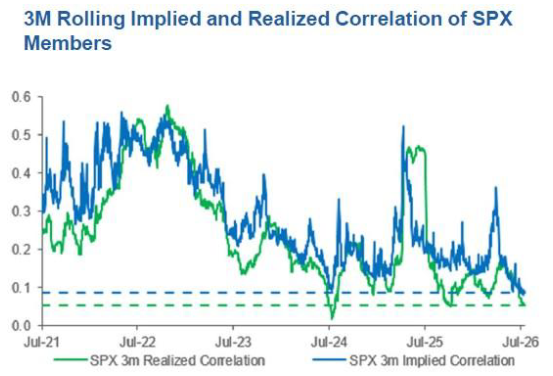
3M Rolling Implied and Realized Correlation of SPX Members. Source: Goldman Sachs
Retail running for the exits while institutions see a buying opportunity
- Following Q1 gating and negative headlines, retail-vehicle redemptions accelerated across the industry in Q2. Changes in redemption activity varied by manager, with some vehicles seeing declining redemption requests but others seeing increases. Redemptions have been driven largely by retail investors along with some very large foreign investors. Institutional investors remain bullish on the asset class, with many seeing the rotation out by retail capital at a discount as a buying opportunity.

